Central bank depository : Clash of the tightens.
SEI’s view
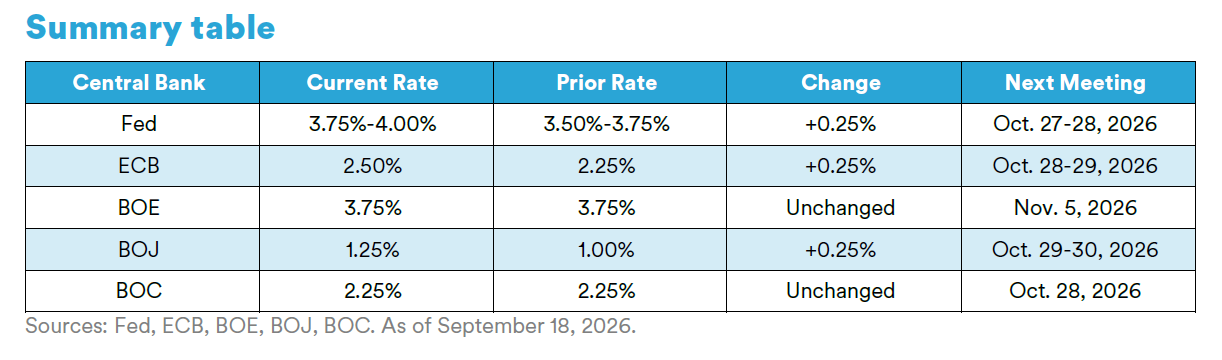
In mid-September, the Federal Reserve (Fed) delivered what was ultimately a well-anticipated first rate hike in three years. Fed Chair Kevin Warsh's tone has shifted notably since his speech at the Jackson Hole Economic Symposium in Wyoming in late August, and a string of stronger-than-expected economic data releases left little room for anything other than a rate hike. The Fed's so-called dot plot of economic projections signals one additional rate hike in 2026, and Warsh reinforced his recent hawkish monetary policy stance, stating that he would be "hard pressed to say broader financial conditions are restrictive." Despite the recent increase in U.S. Treasury yields, SEI continues to believe yields remain biased to the upside over the near term. Offshore, the picture is more mixed. The Bank of England (BOE) elected to keep its policy rate unchanged, maintaining its wait-and-see approach amid a softer labor market and limited evidence of second-round inflationary effects from higher energy prices. The BOE also scrapped plans to sell long-dated gilts as part of an overhaul of its quantitative tightening program after 30-year borrowing costs reached their highest level since 1998. Despite the recent pause in monetary policy tightening, we believe it is likely that the BOE will ultimately rejoin its central bank peers and resume raising interest rates in the near term. The European Central Bank (ECB) increased its benchmark interest rate for the second time this year, citing persistent inflationary pressures, including the impact of higher energy prices. Similar to the BOE, the ECB finds itself in the difficult position of balancing a soft labor market against still-elevated inflation. For now, we expect that restoring price stability will remain its primary focus.
Federal Reserve (Fed)
- In a unanimous vote at its September 15-16 meeting, the Federal Open Market Committee (FOMC) raised the federal funds rate by 0.25% to a range of 3.75% to 4.00% ―its first rate hike since July 2023. In its statement announcing the policy decision, the FOMC noted the continued stability of the U.S. economy. “While uncertainty remains elevated owing, in part, to geopolitical developments, domestic spending has been resilient,” the central bank stated. However, the FOMC cautioned, “Inflation remains elevated. Today’s policy action will support a timelier return to the Committee’s 2 percent goal.”
- The Fed’s so-called dot plot of economic projections indicated a median federal funds rate of 4.1% at the end of 2026, up from its forecast of 3.8% in June, signaling that the central bank anticipates one more rate hike this year.
- During a news conference following the FOMC meeting, Fed Chair Warsh acknowledged that inflation “is too high and has been for too long. Our decision comes at a time when the American economy appears to be strengthening.”
European Central Bank (ECB)
- The ECB voted unanimously to raise its benchmark interest rate by 0.25% to 2.50% at its September 9-10 meeting, citing the Mideast conflict’s ongoing impact on the European economy.
- In a news release, the ECB’s Governing Council commented, “The outlook remains highly uncertain, with risks to the upside for inflation and to the downside for economic growth. In relation to the energy shock, the updated scenarios put together by staff illustrate the broad range of outcomes for how growth and inflation would evolve under different assumptions about its intensity and duration, as well as its indirect and second-round effects.”
- In prepared remarks for a news conference following the rate announcement, ECB President Christine Lagarde and Vice President Boris Vujčić stated, “The conflict in the Middle East and recent developments in Russia’s unjustified war against Ukraine have pushed the path of energy prices up further. This is likely to keep headline inflation well above target into the first half of 2027…We are committed to setting monetary policy to ensure that inflation stabilises at our two per cent target in the medium term.”
Bank of England (BOE)
- At its meeting on September 16, the BOE voted by a margin of 6-3 to maintain the Bank Rate at 3.75%. However, three Monetary Policy Committee (MPC) members supported a 0.25% rate increase. BOE Governor Andrew Bailey noted, “[I]f the conflict in the Middle East persists for an extended period…it is likely that policy may have to tighten.”
- The MPC stated, “Protracted conflict in the Middle East has contributed to further increases in crude and refined energy prices since the previous meeting, which remain more volatile and higher than pre-conflict…Monetary policy is being set to ensure inflation comes down to 2% sustainably as the economy adjusts to the energy shock. The policy stance required to achieve this will depend on the scale and duration of the shock and how it propagates through the economy.”
- The central bank’s announcement provided insights into the views of the MPC members. Catherine L. Mann, who favored a 0.25% rate hike, commented, “Raising [the] Bank Rate is a better risk-management strategy when faced with uncertainty about inflation dynamics and second-round effects. Doing so avoids a worse outcome whereby inflation becomes embedded, which requires even tighter policy later.”
Bank of Japan (BOJ)
- At its meeting on September 17-18, the BOJ’s Policy Board voted by a 7-2 majority to raise its benchmark interest rate to a 31-year high of 1.25%.
- In a statement announcing the rate decision, the central bank noted that there could be more rate increases in the near future. “[G]iven that underlying CPI inflation has been approaching 2 percent and financial conditions have been accommodative, the Bank will continue to raise the policy interest rate and adjust the degree of monetary accommodation, in response to developments in economic activity and prices as well as financial conditions.”
- At a news conference following the meeting, BOJ Governor Kazuo Ueda commented, ”If risks of underlying inflation overshooting 2% materialize, that could have a negative impact on Japan's economy…Our policy phase has changed.”
Bank of Canada (BOC)
- The BOC kept its policy rate at 2.25% for the seventh time in a row at its September 2 meeting.
- In a statement announcing the monetary policy decision, the central bank commented that economic growth in Canada has strengthened and inflation has moved in line with its July forecast. “The continuing conflict in the Middle East is keeping energy prices high,” the BOC stated, “As well, new U.S. tariffs and Canadian counter-measures have been announced following the breakdown of trade talks between Canada and the United States. Both situations remain fluid.”
- At a news conference following the interest-rate announcement, BOC Governor Tiff Macklem said, “[T]he conflict in the Middle East has persisted without a clear path to resolution. Closer to home, the United States has imposed new tariffs on Canadian exports…Monetary policy cannot offset the effects of tariffs or influence global energy prices. What we can do is ensure global developments don’t jeopardize price stability in Canada.”
GLOSSARY AND INDEX DEFINITIONS
For financial term and index definitions, please see: https://www.seic.com/ent/imu-communications-financial-glossary
IMPORTANT INFORMATION
This material represents an assessment of the market environment at a specific point in time and is not intended to be a forecast of future events or a guarantee of future results. All information as of the date indicated. There are risks involved with investing, including possible loss of principal. This information should not be relied upon by the reader as research or investment advice, (unless you have otherwise separately entered into a written agreement with SEI for the provision of investment advice) nor should it be construed as a recommendation to purchase or sell a security. The reader should consult with their financial professional for more information.
Statements that are not factual in nature, including opinions, projections, and estimates, assume certain economic conditions and industry developments and constitute only current opinions that are subject to change without notice. Nothing herein is intended to be a forecast of future events, or a guarantee of future results.
Certain economic and market information contained herein has been obtained from published sources prepared by other parties, which in certain cases have not been updated through the date hereof. While such sources are believed to be reliable, neither SEI nor its affiliates assumes any responsibility for the accuracy or completeness of such information and such information has not been independently verified by SEI.
There are risks involved with investing, including loss of principal. The value of an investment and any income from it can go down as well as up. Investors may get back less than the original amount invested. Returns may increase or decrease as a result of currency fluctuations. Past performance is not a reliable indicator of future results. Investment may not be suitable for everyone.
This material is not directed to any persons where (by reason of that person's nationality, residence or otherwise) the publication or availability of this material is prohibited. Persons in respect of whom such prohibitions apply must not rely on this information in any respect whatsoever.
The information contained herein is for general and educational information purposes only and is not intended to constitute legal, tax, accounting, securities, research or investment advice regarding the strategies or any security in particular, nor an opinion regarding the appropriateness of any investment. This information should not be construed as a recommendation to purchase or sell a security, derivative or futures contract. You should not act or rely on the information contained herein without obtaining specific legal, tax, accounting, and investment advice from an investment professional.
Information in the U.S. is provided by SEI Investments Management Corporation (SIMC), a wholly owned subsidiary of SEI Investments Company (SEI).
Information in Canada is provided by SEI Investments Canada Company, a wholly owned subsidiary of SEI Investments Company (SEI), and the Manager of the SEI Funds in Canada.
In the UK and the EEA this information issued in the UK by SEI Investments (Europe) Ltd, 1st Floor, Alphabeta, 14-18 Finsbury Square, London EC2A 1BR which is authorised and regulated by the Financial Conduct Authority.
The contents of this document have not been reviewed by any regulatory authority in Hong Kong. You are advised to exercise caution in relation to the offer. If you are in any doubt about any of the contents of this document, you should obtain independent professional advice.
This document has not been registered as a prospectus with the Monetary Authority of Singapore.
This information is made available in Latin America and the Middle East FOR PROFESSIONAL (non-retail) USE ONLY by SIEL.
Issued in South Africa by SEI Investments (Europe) Ltd, an authorised financial services provider (FSP No. 9796). This material is general information only and does not constitute financial advice, as defined in the Financial Advisory and Intermediary Services Act, 2002. It has been prepared without taking account of any person’s investment objectives, financial situation or particular needs. Recipients should obtain appropriate independent financial, tax and legal advice before making an investment decision.
Any questions you may have in relation to its contents should solely be directed to your Distributor. If you do not know who your Distributor is, then you cannot rely on any part of this document in any respect whatsoever.